Optimize the impact of CECL capital requirements
One platform to integrate market data, balance sheet and credit losses — built for modern risk teams.
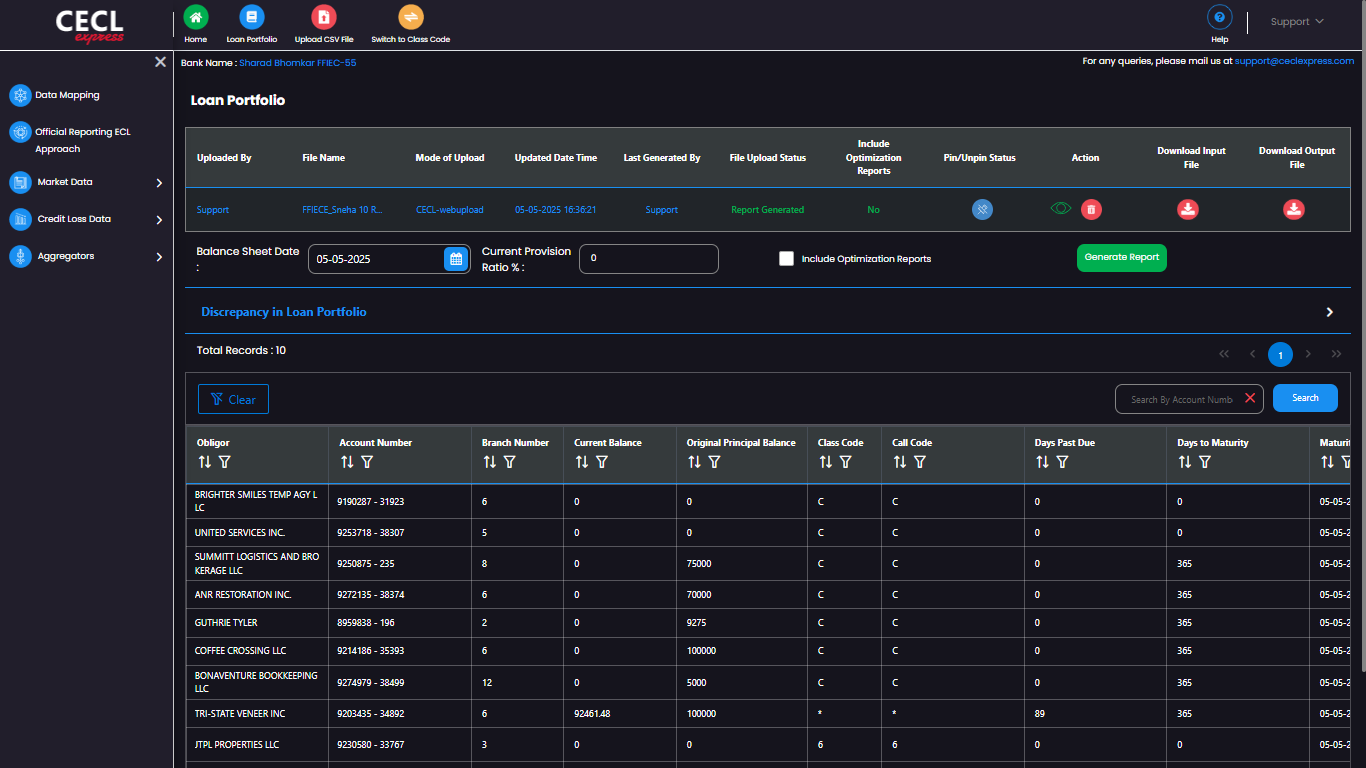
CECL Software for Credit Unions & Community Banks
CECL Express is a purpose-built CECL compliance and allowance forecasting platform that helps financial institutions calculate expected credit losses accurately, consistently, and with full audit transparency.
What is CECL Express?
CECL Express is cloud-based CECL software that enables credit unions and community banks to estimate lifetime expected credit losses using regulator-accepted methodologies and forward-looking economic data.
Why CECL Express Exists
CECL compliance requires more than a calculation — it requires defensible methodology selection, transparent assumptions, and repeatable documentation. CECL Express was designed to simplify this process without sacrificing regulatory rigor.
Core Capabilities
- CECL allowance forecasting across multiple methodologies
- Portfolio segmentation and loan-level modeling
- Qualitative factor (Q-Factor) adjustments
- Economic forecast integration
- Audit-ready reporting and documentation
- Examiner-friendly outputs
Who CECL Express Is For
- Credit unions preparing for CECL exams
- Community banks seeking scalable CECL software
- Finance and risk teams needing defensible allowance workflows
- Institutions transitioning away from spreadsheets
Built for modern risk teams
One platform that brings every input — market data, balance sheet, scenarios — into a single, auditable CECL workflow.
Seamless
- Fully integrated with Finastra Phoenix for touch-free implementation
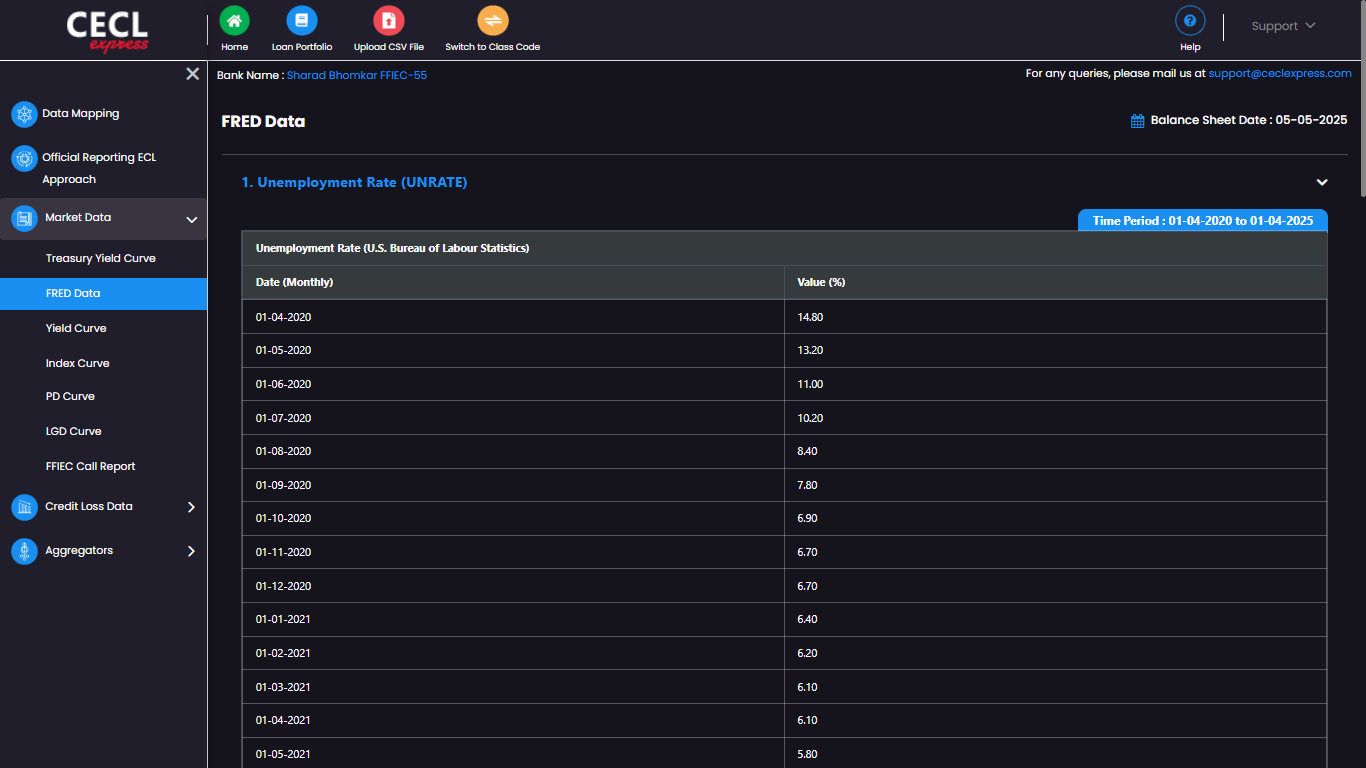
- Data from Fed, FRED and FFIEC built into the solution
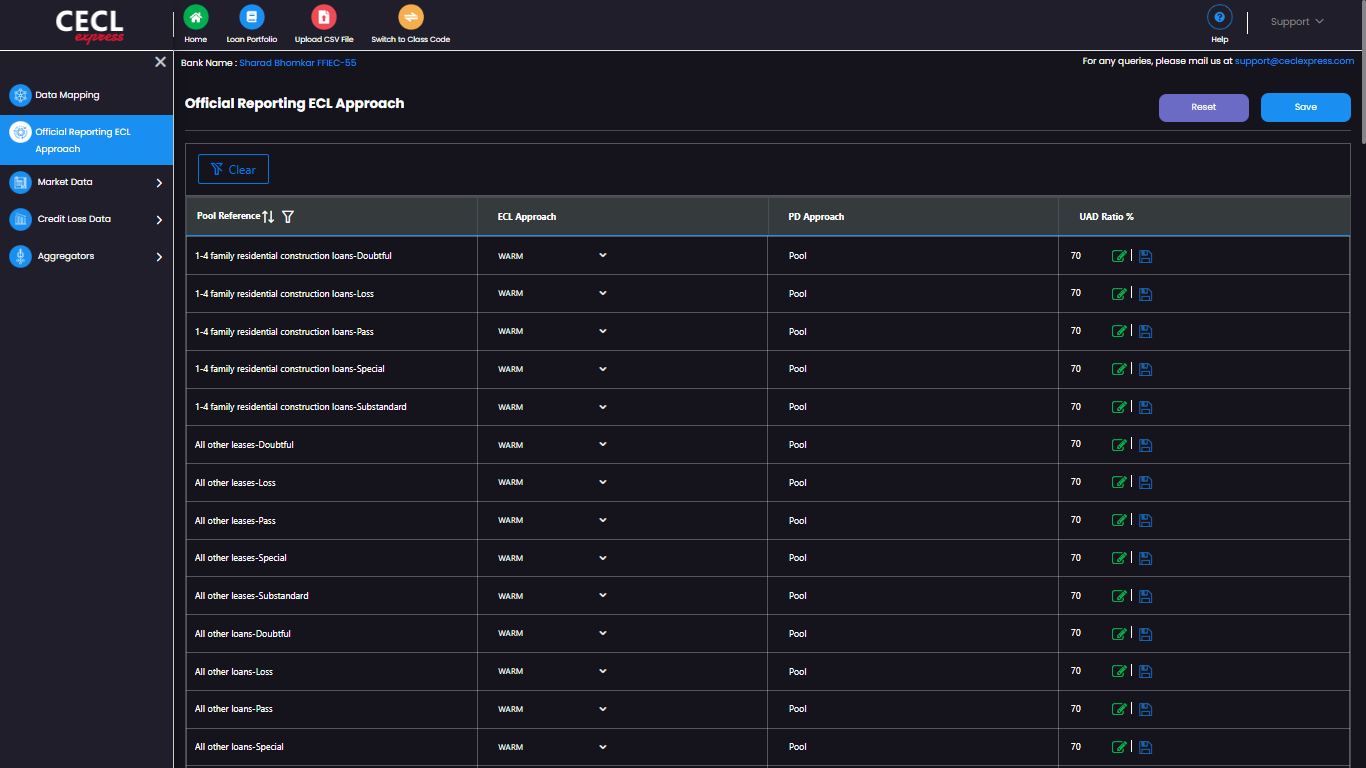
- Full user control over loan pooling, Q-factors, and scenario definitions
Optimized
- Calculates capital for multiple CECL methods by pool for each scenario
- Graphical and tabular breakdown for the lowest, most efficient CECL projection
- Detailed breakdown for each pool and scenario
Intuitive
- Designed to provide effective CECL reporting out of the box
- Built on Power BI for an intuitive, click-through user experience
- All data and inputs readily accessible for full auditability
Road to CECL
- CECL is a regulatory measure in response to the 2008 credit crisis.
- FASB's mechanism to account for possible future credit losses.
- Drives the need for higher capital provision across the US banking sector.
Analysis: Banks held insufficient capital to cover credit-related losses.
Stress Testing (DFAST). Liquidity Ratios (LCR and NSFR).
IFRS9 — IASB. CECL — FASB.
CECL Implementation Schedule
Hover or tap a phase to explore what it involves. Non-SEC filers must officially report CECL numbers from December 31, 2022.
Implementation considerations
- Banks must pool their loans appropriately.
- Banks must select the most suitable CECL methodology at the pool level.
- Banks may apply location-specific qualitative factors to the macro-economic data used within these methodologies.
Ready to simplify CECL?
Talk to our team to see how CECL Express fits your stack and your reporting calendar.