Liquidity and CECL
The Financial Accounting Standards Board (FASB) considers a few parameters as necessary for calculating expected credit losses for banks and other financial institutions while implementing the Current Expected Credit Losses (CECL) accounting standard. These parameters are listed below:
- Current conditions
- Historical experience and information about past events
- Reasonable and supportable forecasts
CECL measures expected losses related to financial assets, but because it measures how much capital to hold as a bank, it can also be seen as a liquidity measure. Therefore, it can influence if financial institutions are going to be short of capital after estimating their reserves and if that could lead to a capital problem and a liquidity problem. Once institutions consider this liquidity aspect that accompanies CECL implementation, they can prepare for any adverse situations that may arise in the future.
Constructing scenarios while planning CECL
The collectability of financial assets will depend on the adjustments of reasonable and supportable forecasts along with the historical loss rates. This can be achieved by modeling elements such as stress scenarios and economic shocks. Historical loss information should be adjusted, as necessary, to reflect the reasonable and supportable forecasts that are not already reflected in the historical loss information. Qualitative and quantitative factors will have to be incorporated when estimating CECL allowances.
Although no specific estimation methods are prescribed under CECL, the allowances for credit losses can be determined using several reasonably accurate methods. Some of these methods include:
- Probability of default/loss given default method
- Loss rate method
- Vintage analysis
- Roll-rate method
- Discounted cash flow analysis
Any of the above estimation methods can be applied to different financial asset groups, provided the bank's credit loss estimates are well supported. Banks can develop several defensible scenarios based on the right economic theory to become CECL compliant. These scenarios help them assess lifetime credit losses using various assumptions. In a recession, several macroeconomic factors can work against the recovery of credit in banks. As a result, default probabilities increase, and losses in the event of a default worsen.
For example, if 0.1 percent of people default on a credit score of 800 or 750 during a regular time, 0.2 percent of people default in a recession because they are being impacted by all the negative economic factors that follow a recession.
Credit loss data lags recessions
Losses that drive expected loss calculations by their very nature lag recessions and potentially leave banks unprepared for the impact. All the indicators in terms of how people default lag the market. Banks can build scenarios that actually facilitate the estimation of losses. They have to factor in what happens when GDP falls, if default ratios increase, if loss-given defaults go up, and when house prices fall. All of this data needs to be factored into the system.
Liquidity and the benefits of constructing scenarios
Liquidity basically means how much cash banks have ready in their system to use for any contingencies and investment purposes. If their CECL provision goes up, they will have less cash. Some of the factors that can influence liquidity within banks and, consequently, CECL provisioning include:
- Disposable incomes
- Size and complexity of portfolios in institutions
- Unemployment
- Inflation
- Market volatility
Constructing scenarios for internal uses allows banks to do two things:
- Monitor liquidity buffers
- Select CECL methods that are least sensitive to deteriorating conditions
A bank's liquidity contingency plans include the following:
- Identifying contingent liquidity events
- Assess funding needs by judging the severity of these events
- Identify potential sources of funds, such as loans that could be sold off
- Establish a mechanism to monitor and manage events
Banks can increase liquidity within their system and be prepared for any contingencies by using the below-listed measures:
- Sale of assets
- Reduction in cash consumption activities
- Bond issuances
- Setting up crisis management committees
- Conducting dry runs of liquidity stress tests periodically
CECL is all about planning
To conclude, there is more to CECL than just reporting. There is actual planning. There is the planning of CECL itself, which impacts the model, and there is the planning of liquidity. Liquidity contingency plans can be managed effectively through proper supervision and regulation. So, whenever we choose or design a CECL solution, we should think about the additional liquidity requirements that can be incorporated by that solution.
CECL Express can help…
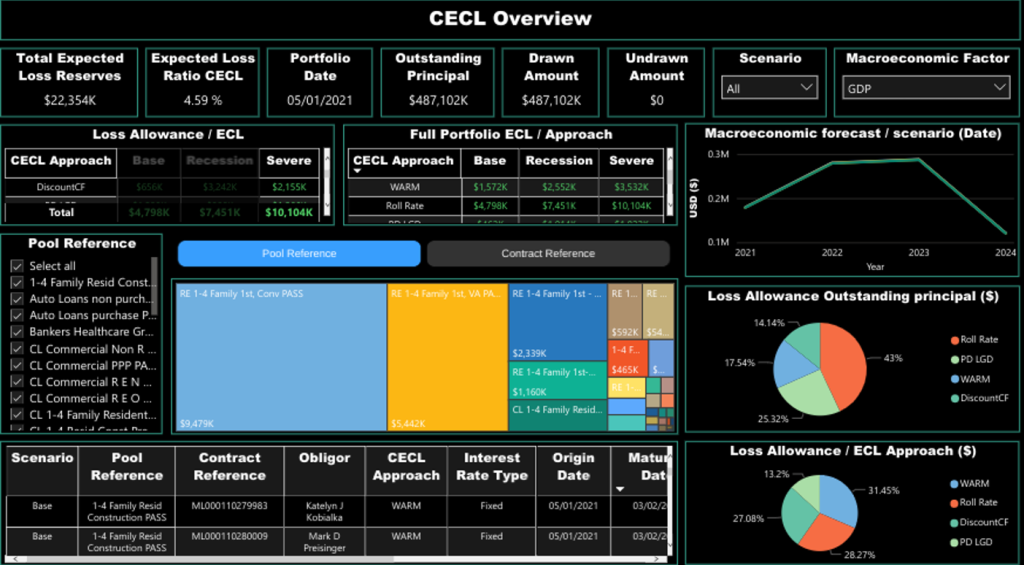
CECL Express is a turnkey solution that fully satisfies all elements of the new CECL accounting standard. The system provides all non-loan data, including:
- Yield curves and Fed data
- Linked reports on losses from the FFIEC and NCUA
- PD and LGD curves
- Macroeconomic data
Banks and credit unions need to only provide the underlying loan details for the system to provide fully auditable ECL results for multiple calculation methods, including:
- Vintage
- Roll Rate
- Discounted Cashflow
- WARM
- PD/LGD
CECL Express provides more than valid ECL results. The system computes results for all methods and all loan pools, allowing the bank to optimize its CECL configuration and avoid the worst impacts of the new standard.