CECL Implementation
After the financial crisis of 2008, it was widely agreed that it had been aggravated by the incurred loss methodology existing then, which delayed the recognition of credit losses. The Financial Accounting Standards Board (FASB) worked along with the International Accounting Standards Board (IASB) to come up with a forward-looking way of measuring credit losses. The FASB announced an Accounting Standards Update (ASU), now known as the Current Expected Credit Losses (CECL), to calculate expected credit losses, which are part of an institution's financial assets.
The deadline for implementing CECL is not far away. Some financial institutions have already implemented CECL, many are in the process of implementing it, and yet more are yet to start with their implementation process. There are a few basics that institutions have to keep in mind as they plan a road map for implementation.
a) Model selection
The FASB has recommended several models under CECL to calculate reserves that would be needed to cover any future expected credit losses:
- Discounted cash flow analysis
- Loss-rate method
- Vintage analysis
- Probability-of-default method
- Roll-rate method
Financial institutions, according to their size, can scale CECL and apply it. Small institutions, in fact, are not required to apply any complex modeling techniques. While choosing a model, banks will need to use their judgment, keeping in mind the complexity and data capabilities of their organizations.
b) Data validation
- CECL requires advanced data validation, assessments, and interpretation.
- Institutions need to determine and organize all available internal data that is required to successfully run their CECL models.
- In case of any shortage in internal data, banks can look at external data resources to bridge the gap.
- Data on the level of segmentation for loans that possess similar risk characteristics is needed.
- Data to support an institution's forecasts and asset segmentation is required.
c) Solution design
The next step is to design the solution to suit models and data that is made available from institutions. Some firms have the requisite resources to build a CECL implementation solution themselves, while others must purchase it. Banks can select solutions ranging from sophisticated modeling software to internally developed spreadsheets.
d) Trial runs
After the solution design, institutions can commence the trial run. It is a stage when it is still possible to change anything if needed. One way to perform trial runs would be to develop certain model CECL scenarios and then run historical data through this model. The next step would be to compare the results to the expected performance.
e) Tweaking
After analyzing the results of the trial run, institutions can then tweak the solution and processes and tighten up everything to ensure it works seamlessly. Post this, the solution and models are locked into place.
f) Parallel run and going live
Once institutions have identified their models, performed trial runs, and made the necessary tweaks, they can move to parallel runs by testing and comparing the results to those of their current model. As long as the parallel run is successful, the CECL implementation can go live.
Steps when left with too little time to implement CECL
When institutions are left with very little time to put a CECL solution into place, it will be very difficult to build something up themselves at the last moment. The shortcut is that banks and credit unions use the solution from a third-party provider that has already got solutions up and running live. This means that at least the important steps have been checked and verified by the provider.
With little time left, institutions need to find a third-party provider that can, first of all, make sure that it can map their portfolio. Financial institutions must have some idea in mind about the result they are expecting. Broadly speaking, it should be within 25 percent of their current result.
Things financial institutions should avoid as they implement CECL
- Banks should not go with a solution that limits their model choices. They might end up stuck with an inefficient model and possibly even a model that is not fit for their portfolio.
- Institutions should not get trapped into a contract that will cost them more in the future when it comes to adding additional models.
- Banks need to do their best to get a system that tells them more about their portfolio than just the CECL result, including stress testing and other capabilities.
CECL Express can help…
CECL Express is a turnkey solution that fully satisfies all elements of the new CECL accounting standard. The system provides all non-loan data, including:
- Yield curves and Fed data
- Linked reports on losses from the FFIEC and NCUA
- PD and LGD curves
- Macroeconomic data
Banks and credit unions need to only provide the underlying loan details for the system to provide fully auditable ECL results for multiple calculation methods, including:
- Vintage
- Roll Rate
- Discounted Cashflow
- WARM
- PD/LGD
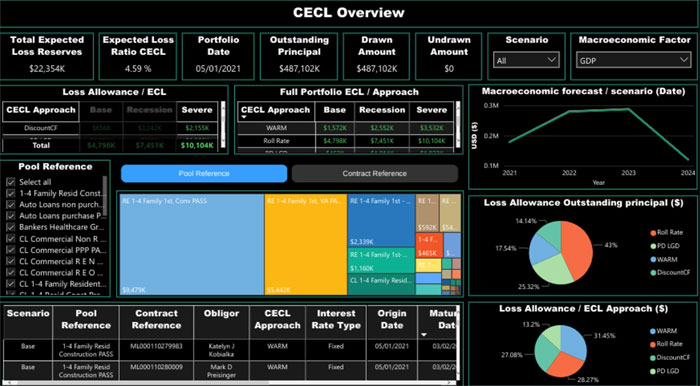
CECL Express provides more than valid ECL results. The system computes results for all methods and all loan pools, allowing the bank to optimize its CECL configuration and avoid the worst impacts of the new standard.